All Categories
Featured
Protecting Income From 2026 Bankruptcy Garnishment
Table of Contents
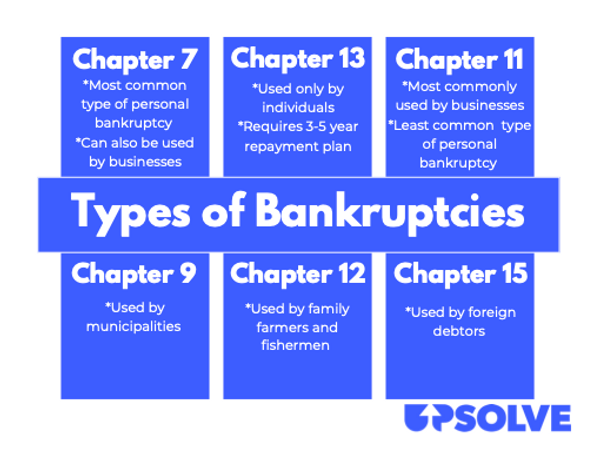
In filing a chapter 11, the debtor provides a plan to creditors which, if accepted by the creditors and approved by the court, will permit the debtor to reorganize individual, financial or business affairs and once again become an economically efficient person or business.: Chapter 12 is designed for "family farmers" or "household anglers" with "regular yearly earnings." It makes it possible for financially distressed household farmers and anglers to propose and bring out a plan to pay back all or part of their financial obligations.
Generally, the strategy must attend to payments over three years unless the court approves a longer duration "for cause.": A private with a regular earnings who is gotten rid of by debts, but thinks such financial obligation can be paid back within an affordable time period, might file under chapter 13 of the bankruptcy code.
If the court approves the strategy, the debtor will be under the court's protection while paying back such financial obligations. More info concerning the distinction in between chapters can be found in the Bankruptcy Fundamentals Handbook.
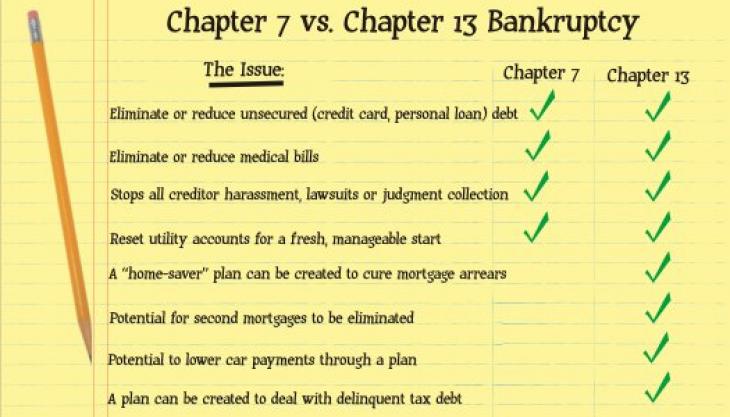
Key Impacts of Filing Debt BankruptcyMany individuals in Michigan reach the point where they know they require relief, however they are stuck on one essential question: should they file Chapter 7 or Chapter 13? Selecting the wrong path can have genuine effects for a home, a vehicle, and an income.
Potential Legal Impacts of 2026 Bankruptcy
You would like to know what these chapters would in fact do to your debts, your credit, and your daily life. You might have heard buddies, colleagues, and even other legal representatives offer strong viewpoints about one chapter or the other, typically with no mention of Michigan exemptions, local trustees, or how your precise mix of debts will drive the choice.
Both chapters originate from federal law, however they do not play out the very same way for each filer. Hensel Law Office, PLLC regularly works with Michigan citizens to compare both chapters side by side using real numbers, not generic checklists, and this article will show you how that analysis works and how to prepare for it.
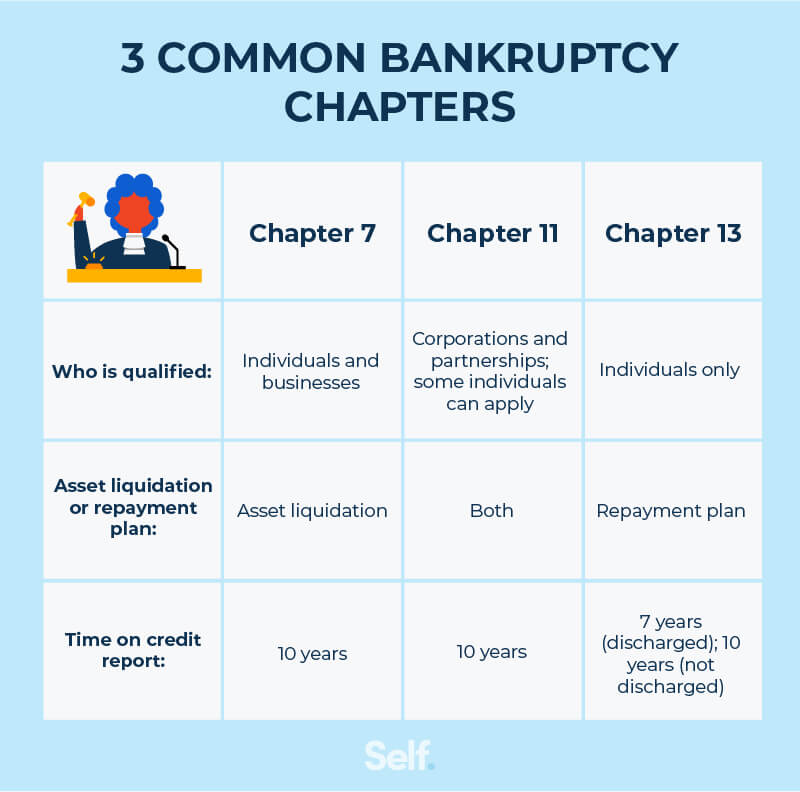
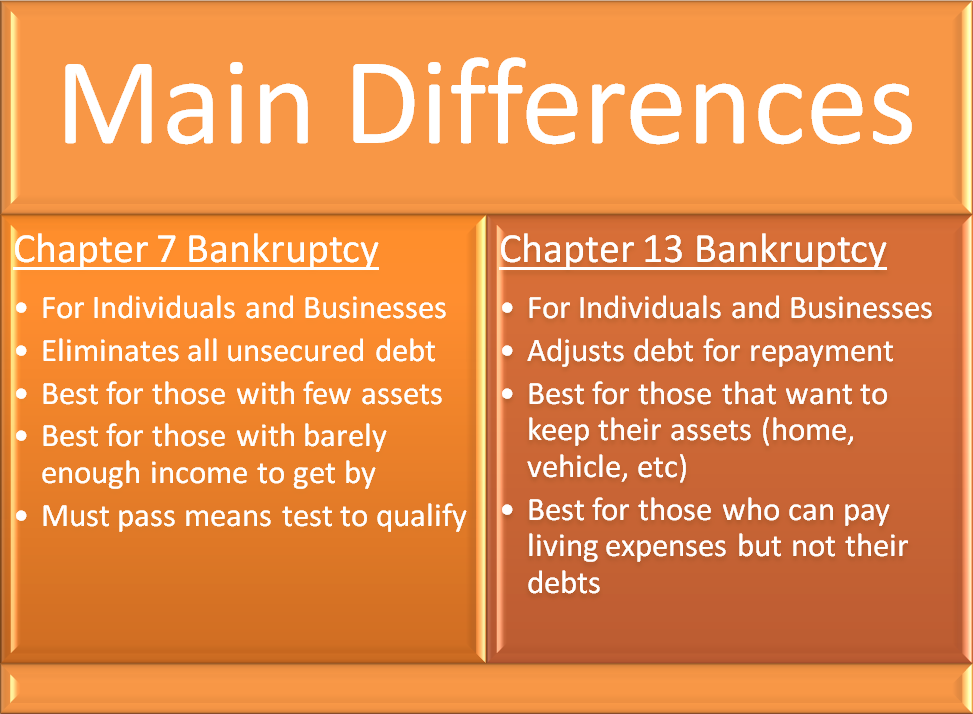
When you submit Chapter 7 in Michigan, a bankruptcy estate is produced that momentarily includes your non-exempt property, and a trustee is designated to examine your possessions, income, and current monetary history. In lots of Michigan cases, exemptions cover whatever the person owns, so the trustee does not sell anything, however that depends on your equity levels and the exemptions you use.Chapter 13 is various.
Navigating Between 13 and Chapter 13 for 2026
Rather of focusing on offering non-exempt possessions, Chapter 13 centers on your future income. You propose a monthly payment that fits your budget plan and that satisfies legal tests for paying protected, concern, and unsecured debts. At the end of an effective strategy, staying qualifying unsecured debts are released, similar to in Chapter 7. Both chapters are filed in the U.S.
Nevertheless, Michigan-specific exemption rules, regional trustee practices, and typical local debt patterns change how risky Chapter 7 is for your home and how reasonable Chapter 13 payments are for your household. Due To The Fact That Hensel Law Office, PLLC manages both Chapter 7 and 13 cases in Michigan, the goal is not to push everybody into one chapter, however to match the chapter to the filer's genuine circumstance.
The ways test compares your household earnings to the average earnings level for a family of your size in Michigan and after that adjusts for specific enabled costs. If your earnings is listed below the median, you usually pass the ways test. If it is above, a more detailed computation of allowed costs and debts figures out whether a Chapter 7 filing would be presumed abusive.
You should have a regular earnings, and your overall secured and unsecured debts require to be within limits set by federal law. Individuals often wind up in Chapter 13 due to the fact that their income is expensive to comfortably pass the Chapter 7 suggests test, because they submitted a prior Chapter 7 too just recently, or due to the fact that they lag on a home loan or vehicle loan and require a structured method to catch up.
Essential File for Bankruptcy in 2026
In Michigan, family structure matters. A married individual whose partner is not submitting might still require to consist of some or all of the spouse's earnings in the ways test, which can impact whether Chapter 7 is offered. It is also common for somebody to technically get approved for both chapters from an income perspective, yet discover that their properties or debt mix make one option plainly more secure.

Latest Posts

Key Strategies for Bankruptcy
Financial Support for 2026 Chapter 13 Filers
Understanding Bankruptcy Costs in 2026