All Categories
Featured

Picking Chapter 7 for Your 2026 Benefit
Table of Contents
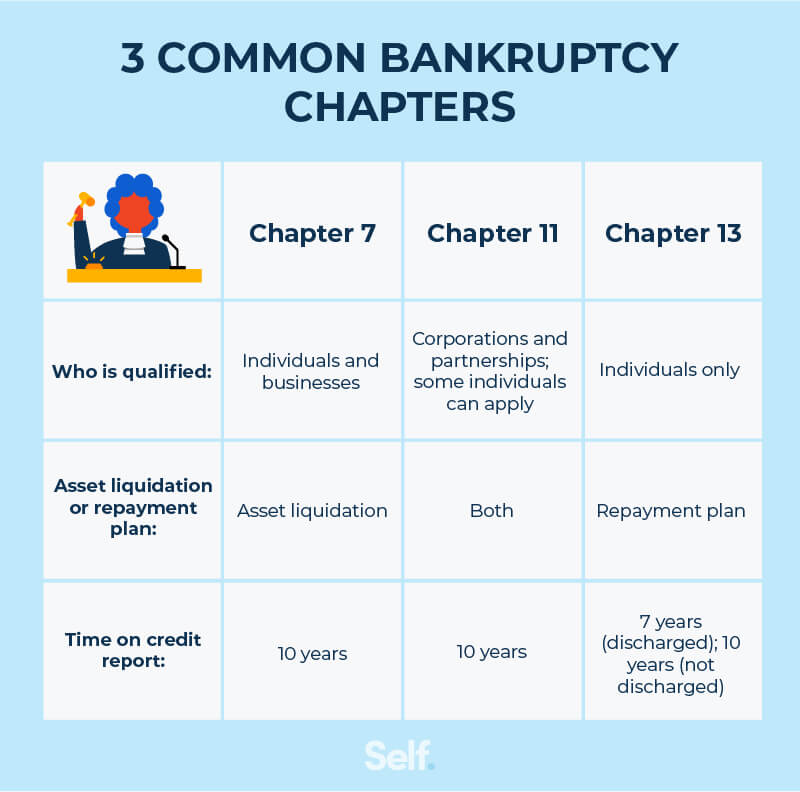
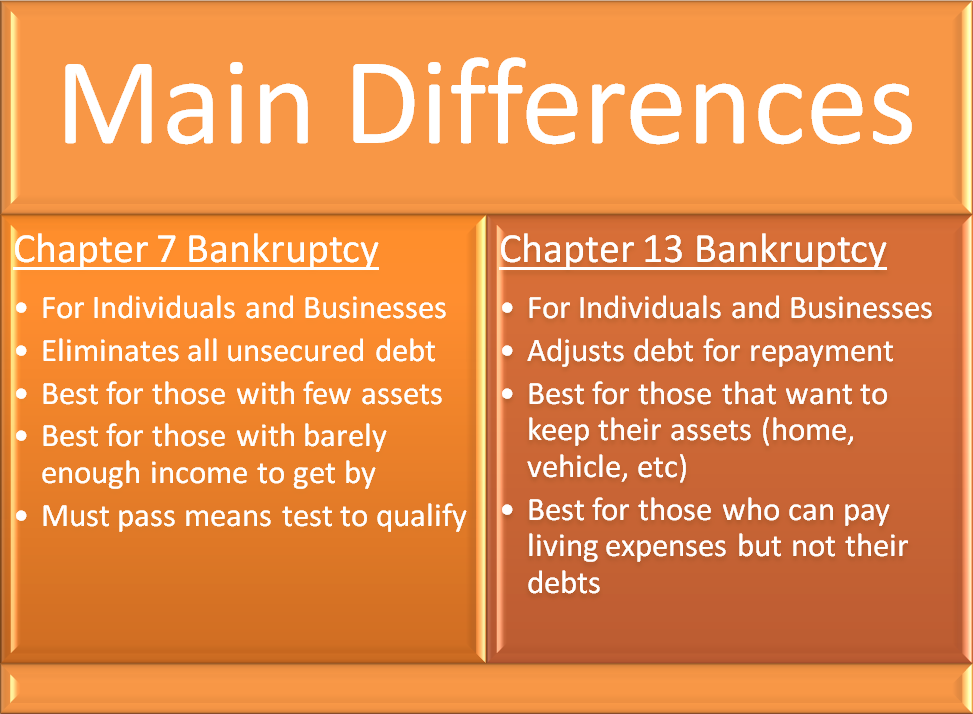
A Michigan occupant with heavy credit card and medical financial obligation, present on all protected debts, and with few possessions, often gets one of the most advantage from a tidy Chapter 7 discharge. In contrast, a homeowner who is numerous months behind on a mortgage however wishes to stay in the home might rely on Chapter 13 to spread out the catch-up payments and stop a foreclosure.
A family renting in Grand Rapids, with 2 vehicle loans that are current and a big pile of credit card and medical debt from a local healthcare facility system, may discover Chapter 7 provides quick relief with little property risk if exemptions cover their modest property. A property owner outside Detroit who has equity above the offered homestead exemption and is behind on the home mortgage might be better served by Chapter 13, which enables them to secure the additional equity and cure arrears over a number of years.
Hensel Law Office, PLLC regularly constructs these side-by-side contrasts with real numbers so you can see which course fits your objectives and restrictions. Misunderstandings about insolvency keep many people from even exploring their alternatives. One of the most widespread misconceptions is that Chapter 7 constantly suggests losing your home or car.
Deciding Between Chapter 7 and 7 for 2026
The risk occurs when equity surpasses what exemptions cover, or when payments are already far behind. That is why a mindful appearance at equity and exemptions is necessary before choosing Chapter 7. On the other side, individuals frequently think that Chapter 13 indicates paying every debt completely, which can make it sound meaningless compared to Chapter 7.
The plan needs to still fulfill legal tests, particularly for secured and top priority financial obligations, but it is not just a five-year payment plan for the total of every expense. Another typical belief is that you can merely pick whichever chapter you prefer. In fact, the law puts guardrails around that option.

Debt limits, earnings stability, and reasonable budgeting limit access to Chapter 13. Some Michigan filers are technically qualified for both, however their properties, financial obligations, or nondischargeable debts make one chapter plainly more useful. An additional trap is assuming that any Chapter 13 plan that looks good on paper will succeed.
Making use of experience with Michigan trustees, Hensel Law Workplace, PLLC helps clients prevent those pitfalls by challenging unrealistic assumptions early and suggesting the chapter that they can actually finish to discharge. As soon as you have a basic sense of how Chapter 7 and Chapter 13 compare in Michigan, the next action is getting particular.
Long-Term Impacts of 2026 Bankruptcy
You will be able to see, for example, whether your home equity is totally safeguarded, just how much a realistic Chapter 13 payment may be, and which debts would survive in either chapter. This grounded contrast is far more reputable than online calculators or national short articles that do not account for Michigan-specific rules.
It is a method to comprehend your real alternatives and the likely timeline before garnishments, suits, or foreclosure move even more. Hensel Law Office, PLLC uses a structured consumption procedure that strolls you through the needed documents and questions so absolutely nothing essential is missed. That preparation helps avoid surprises that might derail a Chapter 13 strategy or produce asset problems in Chapter 7, and it puts you in a position to make a clear, confident decision.
Estimating Current Bankruptcy Lawyer CostsIt has to do with matching the law to your earnings, assets, and debts so you can protect what matters most and move forward. When you comprehend how exemptions safeguard your property, how each chapter treats your specific debts, and what daily life appears like throughout a case, personal bankruptcy becomes a structured tool instead of a secret.
After you collect your fundamental financial details, contact Hensel Law Workplace, PLLC at ( 888) 258-0651to examine your circumstance and see how each chapter would really play out for you under Michigan law. You do not have to guess which choice is.
Navigating Attorney Fees in 2026
Chapter 7 bankruptcy is a process to have actually the financial obligation discharged while maintaining your home and other possessions by making the most of California insolvency exemptions. Since the insolvency court performs all conferences on Zoom, you will not need to appear personally. There is no minimum quantity of debt required to file Chapter 7 insolvency.

Latest Posts

Key Strategies for Bankruptcy
Financial Support for 2026 Chapter 13 Filers
Understanding Bankruptcy Costs in 2026