All Categories
Featured
Navigating Between Chapter 7 and Chapter 13 for 2026
Table of Contents
In Chapter 7, the trustee takes a look at your possessions and compares their equity to the exemptions you declare. Equity is the worth of the residential or commercial property minus what you owe on it. If your equity in a home, car, or other property is fully covered by exemptions, the trustee normally leaves that property alone.
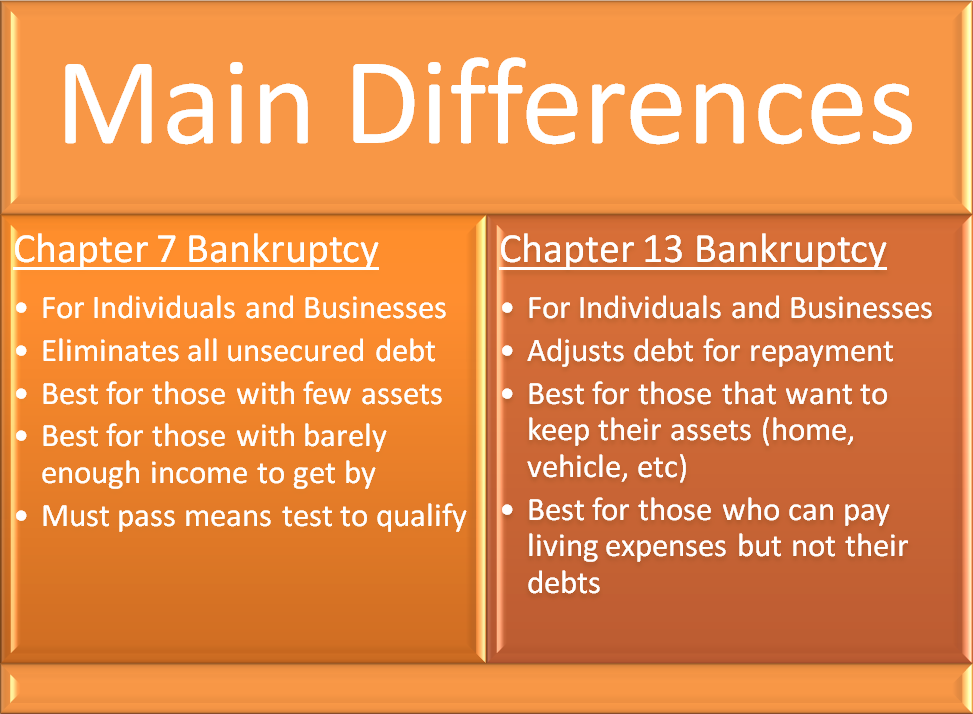
That analysis typically figures out whether Chapter 7 is safe for someone with built-up equity in Michigan property or a paid-off automobile. In Chapter 13, exemptions still matter, but in a various method. Rather of selling non-exempt residential or commercial property, the law normally requires that unsecured financial institutions get at least as much through your plan as they would have gotten if you filed Chapter 7 and your non-exempt assets were sold.

A Michigan homeowner with equity above the homestead exemption may select Chapter 13, make a higher monthly payment for a set number of years, and still keep the home. Since the option in between Michigan and federal exemptions can tilt the balance between Chapter 7 and 13, this is not something to rate.
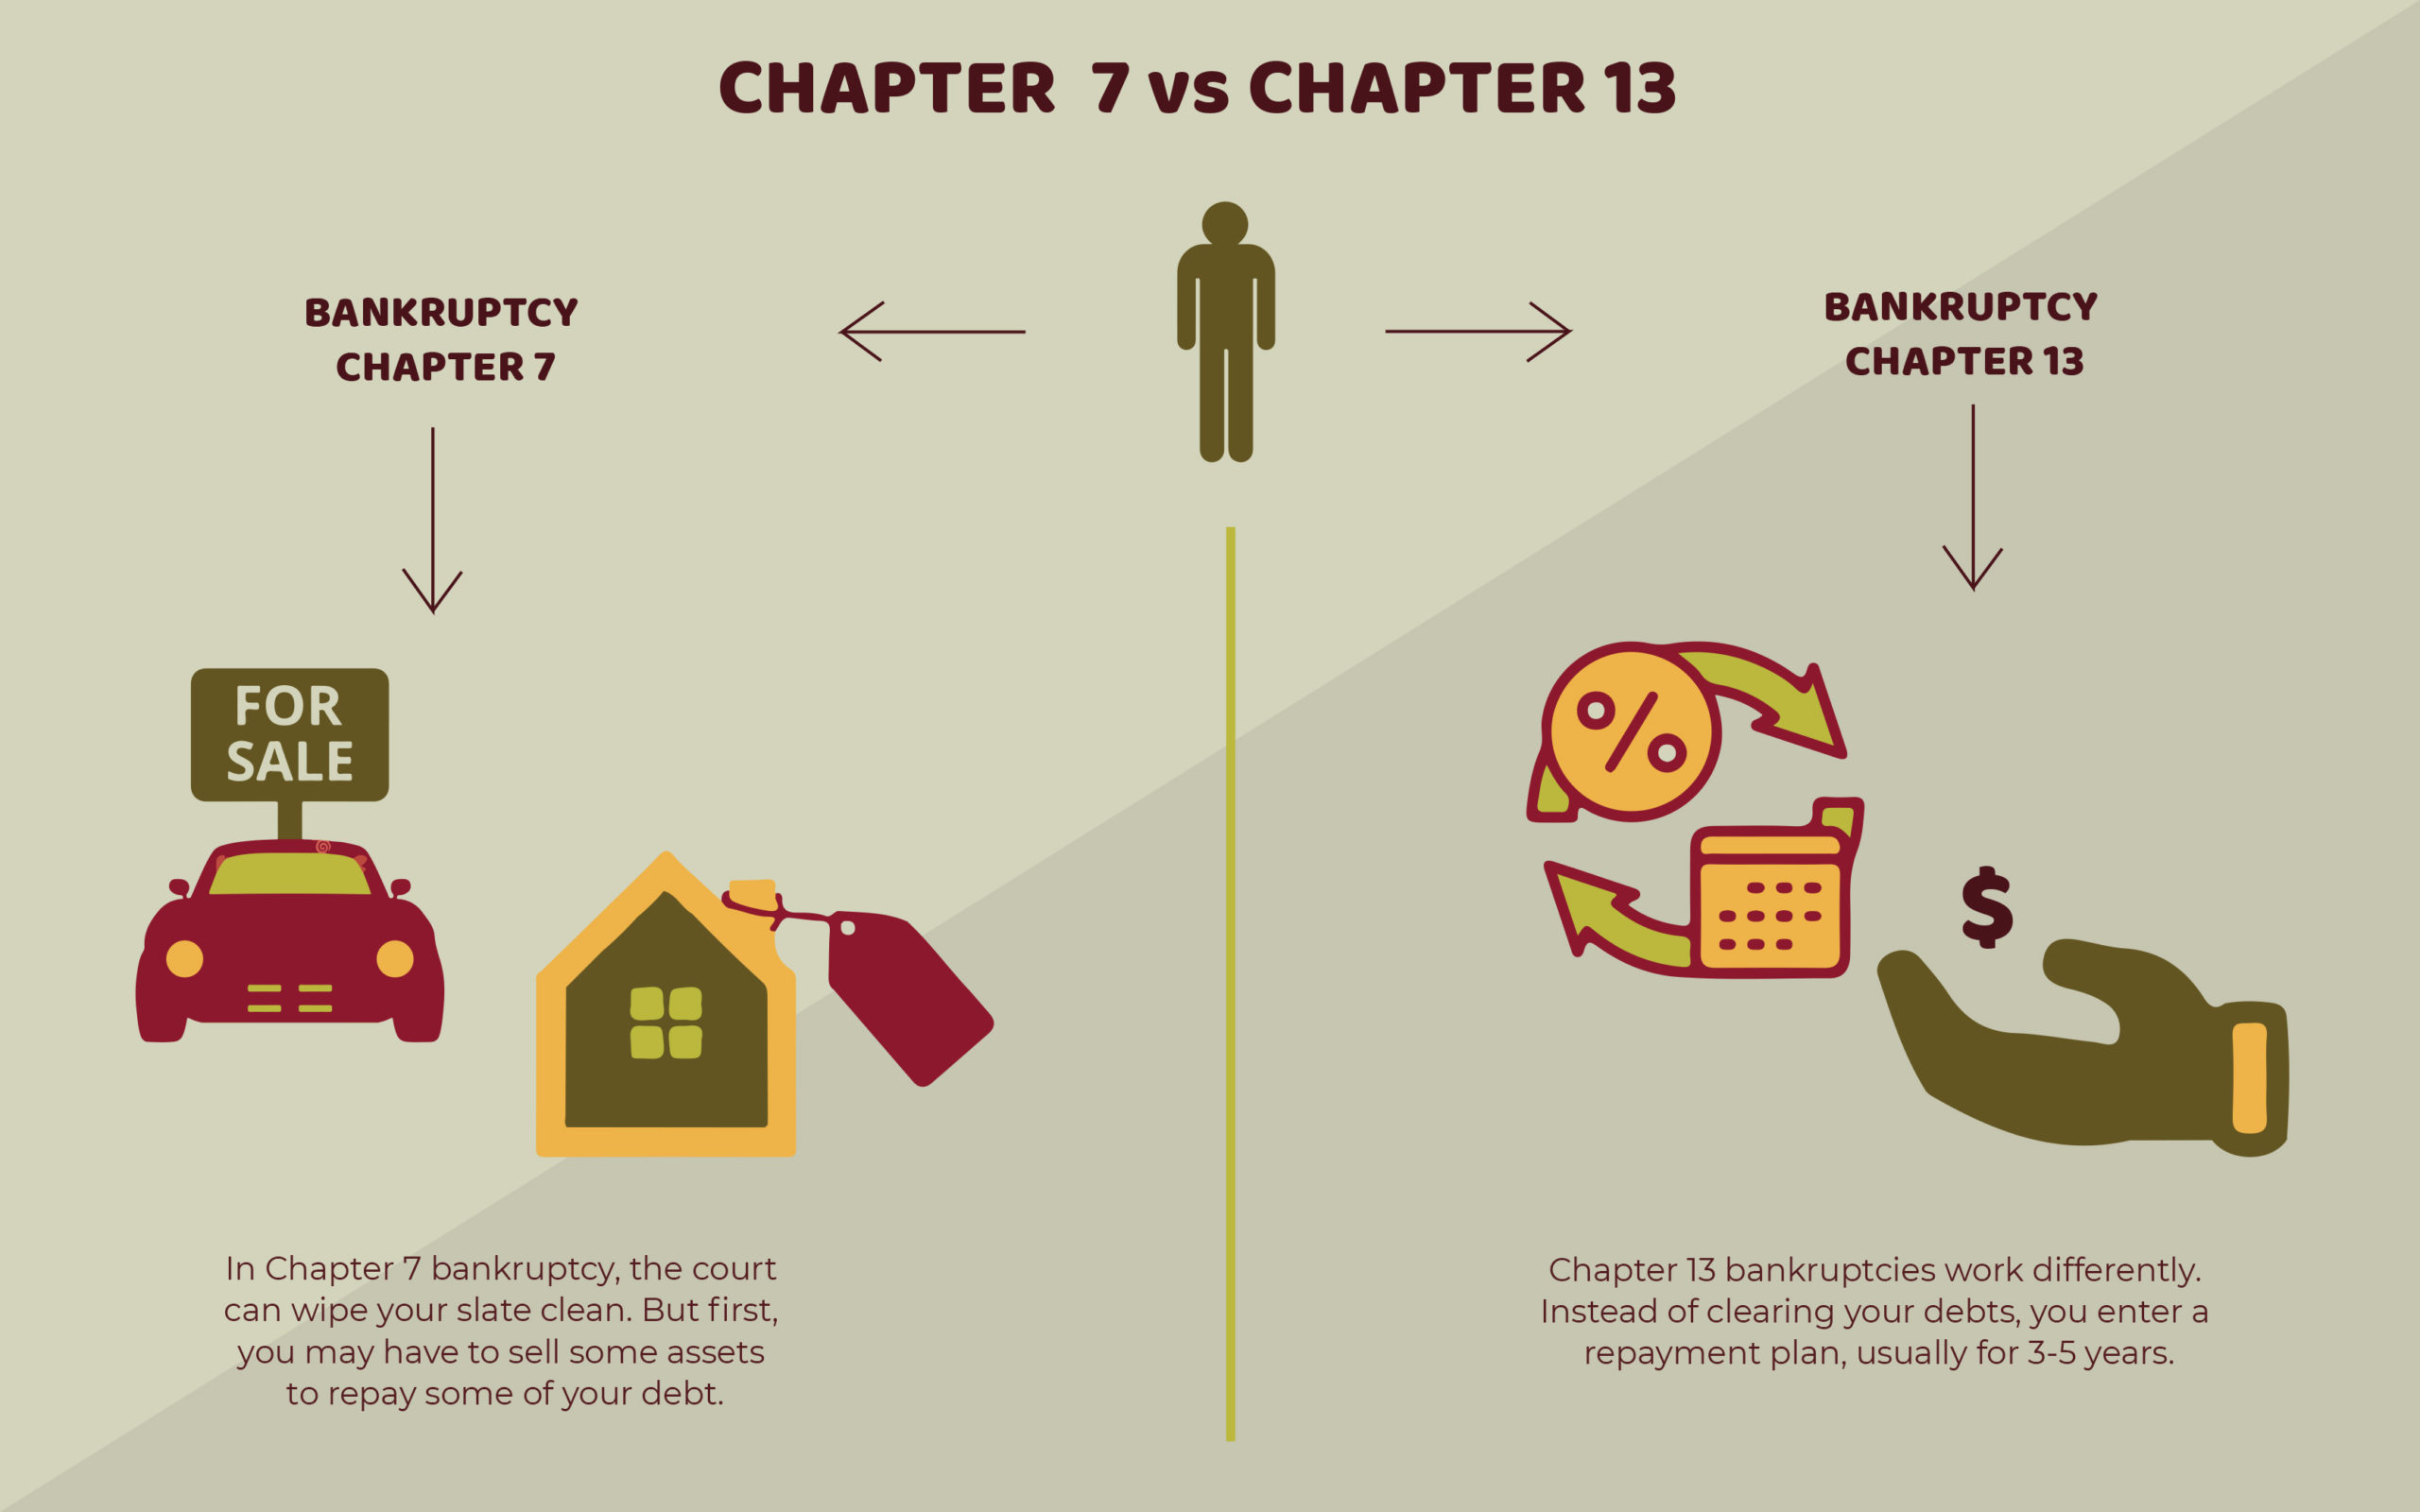
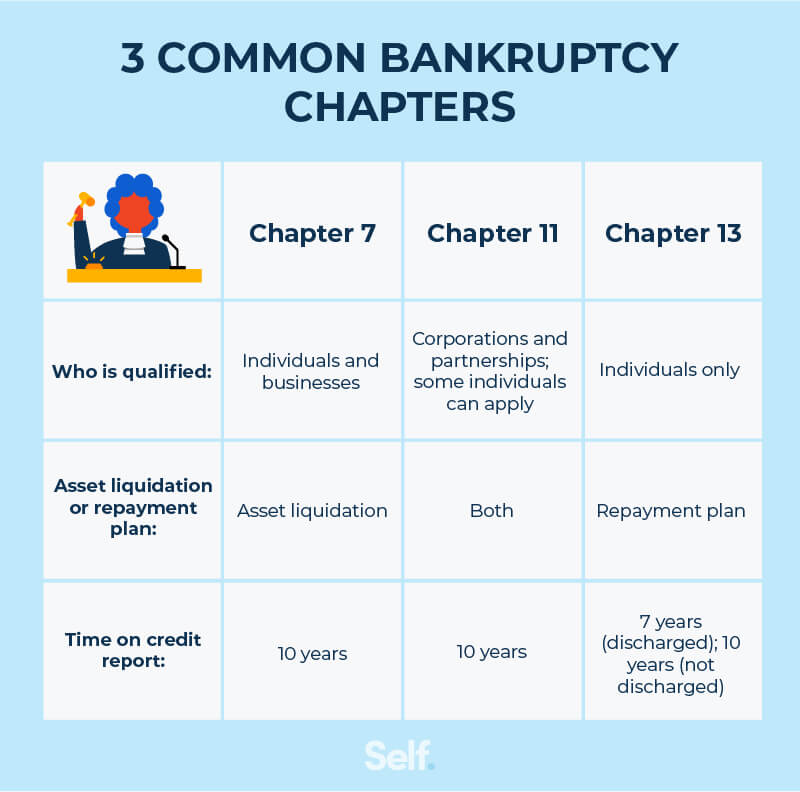
If Chapter 7 looks risky however the client's earnings can support a realistic Chapter 13 payment, the suggestion might move towards Chapter 13 to secure hard-earned property. How each chapter treats your particular debts often matters more than any abstract advantages and disadvantages list. Unsecured debts, such as credit cards, medical expenses, payday loans, and many individual loans, generally get comparable outcome in both chapters, however through different courses.
In Chapter 13, unsecured lenders typically get a share of what you pay into the strategy, which may be anywhere from a little percentage to the complete quantity, and the staying balance can be released at the end if you finish your plan. Guaranteed financial obligations include home that works as security, such as a mortgage on a home or a lien on a cars and truck.
Strategies for Cutting Lawyer Fees in 2026Choosing Chapter 7 Vs Chapter 13 in 2026
Keeping a secured property typically includes staying current on payments and, in some cases, signing a reaffirmation contract that keeps you personally accountable on that particular loan after bankruptcy. If you are far behind and can not capture up rapidly, giving up the property in Chapter 7 eliminates your individual liability for any deficiency balance after the lending institution sells it.
You can expand home mortgage or car loan defaults over a three to five-year strategy, which is called treating defaults, while likewise resuming your regular monthly payments. In some circumstances, Chapter 13 also enables a reduction of certain automobile loan balances to the car's present value, an idea known as cramdown, though comprehensive guidelines apply.
Top priority and nondischargeable financial obligations, such as recent income taxes, kid assistance, alimony, and many trainee loans, stand in a separate category. These are typically not eliminated in Chapter 7, though the automatic stay can pause some collection while the case is pending. In Chapter 13, these debts are often paid in full through your strategy before unsecured creditors get anything.
At Hensel Law Office, PLLC, a detailed creditor list is mapped to these classifications so you see precisely which financial obligations will be removed, which need to be paid, and which chapter handles them more effectively. Knowing how long each chapter lasts and what daily life looks like throughout the case can make the choice feel less abstract.
Strategies for Cutting Lawyer Fees in 2026Soon after filing, the automated stay normally stops garnishments, claims, and a lot of collection calls. You participate in a conference of creditors, typically called the 341 meeting, where the trustee asks questions about your paperwork and finances. After that, you generally await due dates to pass and for the court to issue a discharge, unless the trustee needs more info or is exploring non-exempt assets.
Saving Income From 2026 Bankruptcy Garnishment
You submit the case, and the automated stay enters into result, stopping garnishments, foreclosure sales, and the majority of collection activity. You propose a repayment plan, begin making monthly payments to the Chapter 13 trustee, and attend a 341 meeting and, in a lot of cases, a confirmation hearing where the judge considers whether to approve the strategy.
Lots of Michigan filers are surprised by how structured however workable the everyday reality can be when the plan is realistic. In Chapter 7, your main responsibilities are to be truthful, offer documents, attend your meeting, and finish a required monetary education course. In Chapter 13, the added duties consist of sticking to a budget plan, making every strategy payment on time, and reporting substantial earnings changes.
Once you comprehend how each chapter works, the next action is lining that up with your objectives. One core tradeoff is speed versus structure. Chapter 7 moves quicker and normally involves no long-term payment commitments, which attract Michigan renters and house owners who are present on their home mortgages and have primarily unsecured financial obligations.

Latest Posts

Key Strategies for Bankruptcy
Financial Support for 2026 Chapter 13 Filers
Understanding Bankruptcy Costs in 2026